Are Roth Savings the Best? If You’re in Your 50s with $300k, Here’s Where I’d Save FIRST
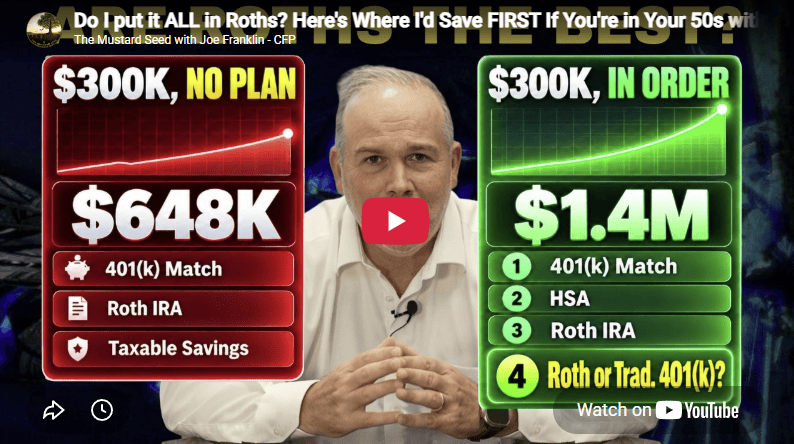
Can you potentially triple your retirement savings between age 50 and 60? The investments you choose matter, but the order in which you fund your retirement accounts could make an even bigger difference.
In this video, Joe Franklin explains how someone starting with $300,000 at age 50 could potentially grow their retirement savings to approximately $1.4 million by age 60 through strategic contributions and tax planning. He compares $25,000 and $50,000 annual savings plans and breaks down how to prioritize a 401(k) match, HSA, Roth IRA, traditional or Roth 401(k), and taxable brokerage account.
Topics Covered:
– The best order for saving toward retirement
– Why the employer 401(k) match comes first
– The triple tax advantages of a health savings account
– Traditional vs. Roth 401(k) contributions
– Roth IRA limits and the backdoor Roth strategy
– Catch-up contributions for people age 50 and older
– When a taxable brokerage account may be beneficial
– How your current tax bracket affects the savings order
– Sample plans for saving $25,000 or $50,000 annually
– Roth conversions during the retirement “golden window”
– Reducing future RMD taxes and potential IRMAA costs
– How strategic saving could help you retire sooner
The right strategy depends on your income, tax bracket, employer plan, health insurance, retirement timeline, and overall financial goals. Planning your contribution order today may help you build more tax-free and tax-advantaged income for retirement.